I’m Justin Leach, a mortgage broker in Santa Barbara. Before I went independent, I spent 12 years as a mortgage banker at Wells Fargo. So when a buyer asks me whether they should get their loan through a bank or a broker, I can answer from both sides of the desk.
Here’s the short version. A bank lends its own money and can only offer its own loan programs. A mortgage broker doesn’t lend money. Instead, I compare loan options across more than 100 lenders I have access to through Xpert Home Lending, and help you choose the one that fits your goals. If you’re getting ready to buy or refinance, call or text me at 805-456-2256.
Broker vs. bank: the basics
The Consumer Financial Protection Bureau puts it simply: a lender is a financial institution that makes loans directly, while a broker does not lend money and helps you find different lenders and loan options (CFPB). The CFPB also recommends shopping around and comparing loan terms, rates, and fees before you choose.
That’s exactly what I do for my clients. Instead of you applying at bank after bank, I do the comparing.
Side-by-side comparison
| A single bank | Justin Leach, Independent Broker | |
|---|---|---|
| Lenders | That bank only | Access to more than 100 lenders through Xpert Home Lending |
| Loan programs | Only that bank’s programs | Conventional, jumbo, bank statement, DSCR, FHA, VA, refinance, and HELOC options across many lenders |
| Guidelines | One set of rules | I compare rules across lenders to find the fit for your file |
| Local experience | Varies by branch and loan officer | 15 years in the Santa Barbara market, plus 12 years at Wells Fargo |
Where I can help most
Many Santa Barbara buyers are in a strong position. They earn well, they’ve saved, and many already own a home. What they need is a lender whose guidelines fit their situation. That’s where comparing lenders makes the biggest difference:
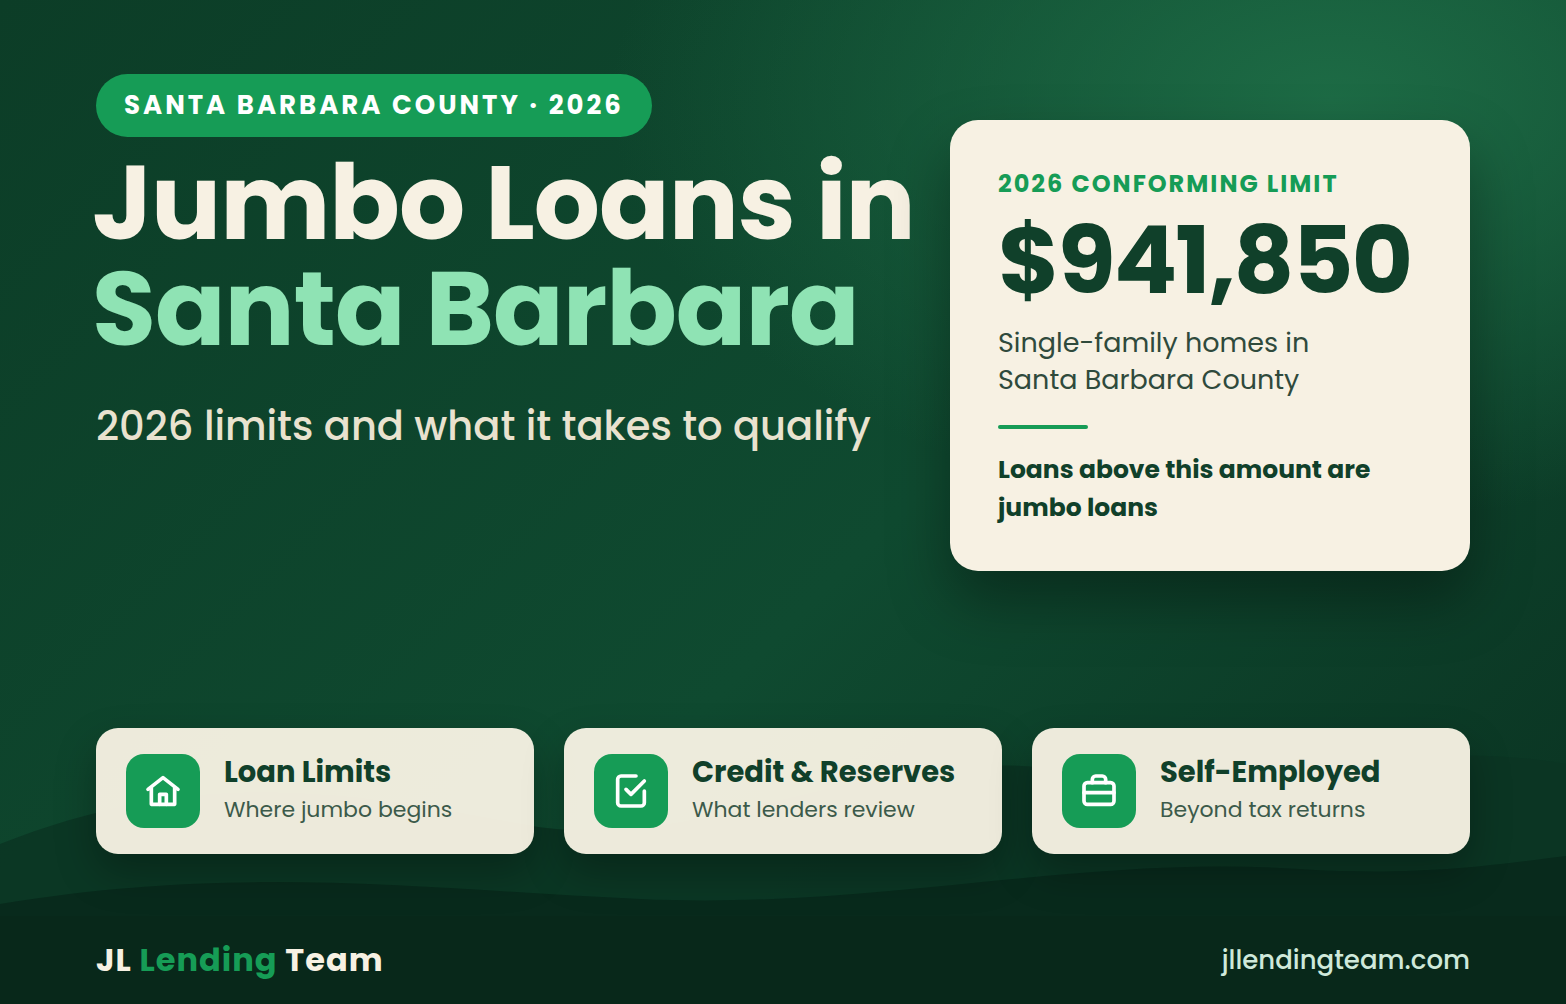
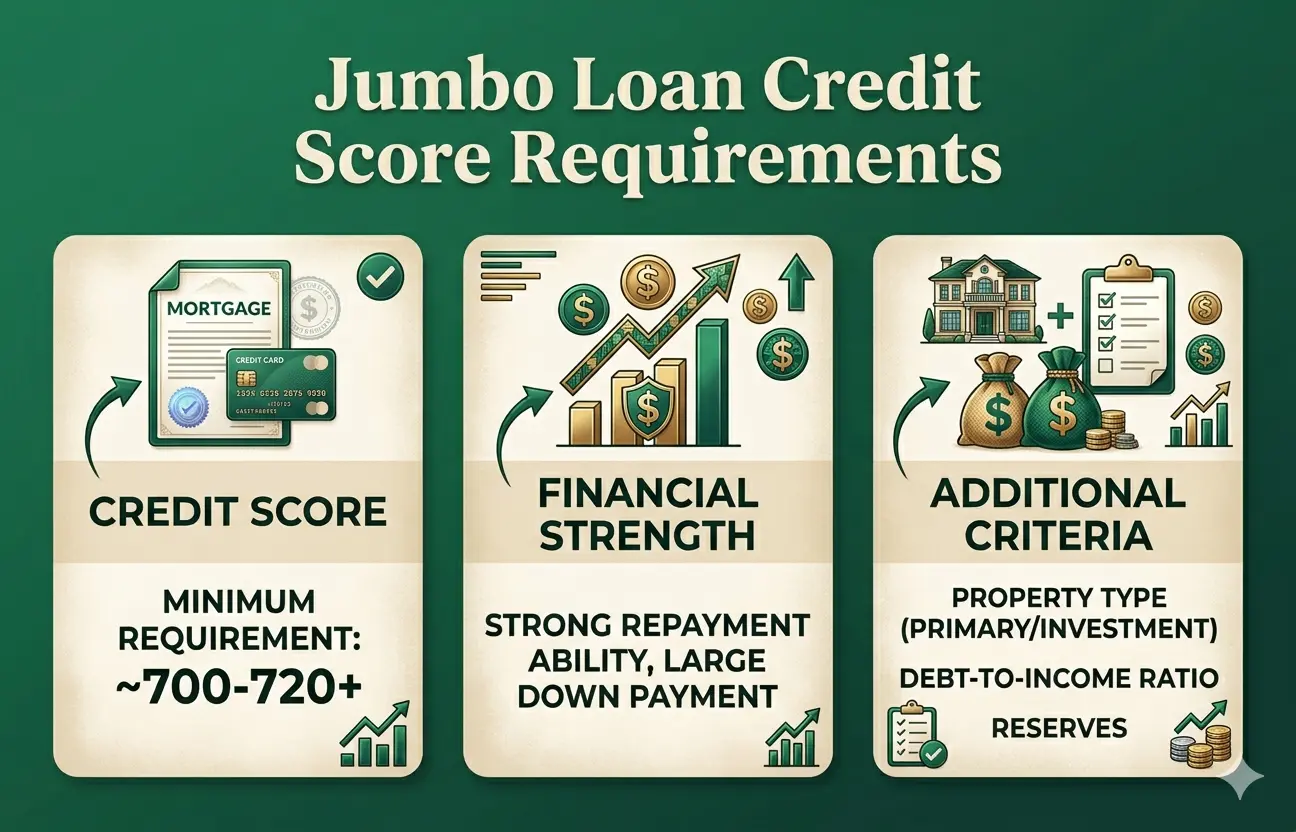
- Jumbo loans. The median Santa Barbara home sold for about $1.8 million over the three months ending in August 2026 (Redfin), and any loan above $941,850 is a jumbo loan in Santa Barbara County. Jumbo lenders set their own rules for credit, reserves, and debt-to-income, and those rules vary a lot.
- Business owners and self-employed buyers. Many banks don’t offer bank statement loans for borrowers whose tax returns don’t show their full income. I work with lenders who do.
- Second homes and investment properties. Programs like DSCR loans, which qualify on a property’s rental income, aren’t offered everywhere.
- Move-up buyers and refinances. Using the equity in your current home takes planning, and the right lender makes it easier.
When your bank may fit
I’ll be straight with you. Some banks offer relationship pricing, such as a rate discount or a closing cost credit, for clients who keep large balances with them (Wells Fargo).
If your bank makes you an offer, send me the Loan Estimate. I’ll compare it with what I can find, and if your bank’s offer is the stronger one, I’ll tell you.
How I work with you
- We talk about your goals. What you’re buying, your timeline, and how you earn your income.
- I review your file. Income, assets, credit, and the property, so there are no surprises later.
- I compare lenders. I look across the lenders I have access to for the programs and guidelines that fit.
- We go over your options. I walk you through each Loan Estimate in plain language before you decide.
- I guide you to closing. I keep you, your agent, and escrow updated from pre-approval to closing.
How brokers get paid
A broker is paid for arranging your loan, either by the lender or by you, and it’s disclosed on your Loan Estimate. Under federal rules, a loan originator can’t be paid by both you and the lender on the same loan, and their pay can’t be based on the terms of your loan, such as the interest rate (CFPB, Regulation Z). That means my job is simply to find the loan that fits you.
Questions to ask any lender
Here are the questions I’d ask if I were shopping, along with my answers:
- How many lenders can you offer me? I have access to more than 100 through Xpert Home Lending.
- Do you offer jumbo and bank statement loans? Yes, along with DSCR, conventional, FHA, VA, refinance, and HELOC options.
- Do you know the local market? I’ve worked in Santa Barbara for 15 years.
- Are you licensed? Yes, in California, Arizona, and Texas. You can look me up on NMLS Consumer Access under NMLS #685345.
Frequently asked questions
Is a broker more expensive than a bank?
Not necessarily. Pricing depends on the lender, the loan, and your file. The way to know is to compare Loan Estimates, and I’m happy to help you do that.
Does a broker service my loan?
No. The lender that funds your loan, or a company it hires, handles your monthly payments. The same is often true with banks, which may sell or transfer loans after closing.
Can you help if I already have a bank offer?
Yes. Send me your Loan Estimate and I’ll compare it with other options.
Do you only work in Santa Barbara?
No. Most of my clients are in Santa Barbara, Goleta, Montecito, Hope Ranch, and Summerland, but I work throughout Santa Barbara County and all of California. I’m also licensed in Arizona and Texas, so I can help you buy or refinance there too.